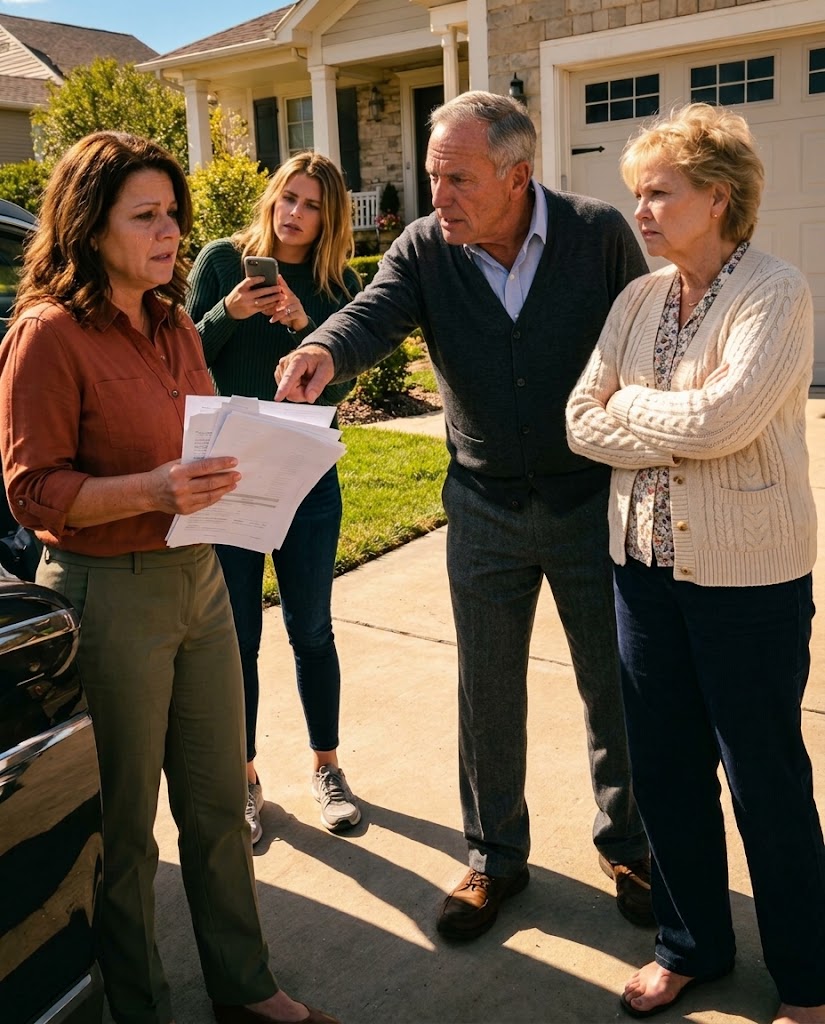
“Ms. Harper, there’s a $100,000 credit account in your name, and someone tried to transfer $45,000 out of it last night,” the bank manager told me at 6:58 in the morning. I stood barefoot in my kitchen while the coffee maker gurgled behind me, trying to understand how an account I’d never opened could already be almost exhausted. Twenty-five minutes later, I walked into Lakeshore Federal carrying my passport and driver’s license, expecting to discover that a stranger had stolen my identity. Instead, I found my mother, father, and younger sister waiting in the lobby, looking as though they’d arranged an appointment together. Mom rose from the couch and complained that the bank had turned a simple family transaction into a fraud investigation, while my sister, Tessa, demanded to know whether her business funds had been released. My father folded his arms and told me there was no reason to make a scene because I could afford to help. Then the branch manager invited me into his office and politely prevented Dad from following. As the door closed, I realized my family hadn’t come to warn me about the debt—they’d come expecting me to approve it.
I’m Lindsay Harper, a thirty-four-year-old civil engineer for the city of St. Louis. I design storm drainage systems, own a modest brick house in Webster Groves, and have spent most of my adult life saving carefully and paying my bills on time. In my family, I was always described as the sensible one. My younger sister, Tessa, was the creative one, praised for her imagination even when she abandoned another class, job, or expensive plan. I earned a scholarship, built a career, and learned to handle problems without expecting anyone to rescue me. Eventually, my parents began treating that independence as an unlimited resource. When their furnace failed, I paid the $7,000 replacement bill. When Tessa faced eviction, I covered $6,400 in rent. Over the years, I also helped with roof repairs, a collapsed sewer line, and unexpected expenses. I didn’t resent helping them. What I hadn’t recognized was how rarely they asked whether I wanted to. The previous autumn, Tessa arrived at my house carrying a beautiful binder filled with photographs, color schemes, and plans for an interior-design studio in St. Louis’s Central West End. She needed $80,000 to get started. I admired her ideas but couldn’t find a workable business budget, reliable revenue projections, or evidence that her proposed clients would cover the rent. I offered to help her prepare a financial plan and connect her with a Small Business Development Center. I refused to lend her the money without those safeguards. She accused me of jealousy and stopped speaking to me for weeks. I thought the matter had ended. But inside Kevin Park’s office at Lakeshore Federal, I saw a credit application dated March fourth, submitted in my name, with a $100,000 limit. More than $55,000 had been charged for furniture, electronics, equipment, and vendor deposits. Another $45,000 transfer had been blocked overnight by the bank’s fraud controls. The receiving account belonged to Harper Design Studio LLC. Kevin showed me the contact details used to verify the application. The telephone number was my mother’s, and the identification document contained my photograph but listed my father’s architecture firm’s address. Even the signature had been imitated. I recognized the distinctive flourish in the handwriting as my mother’s. Verification alerts had gone to her phone, allowing someone with access to it to approve transactions without my knowledge. When Kevin asked whether I’d authorized any of this, I told him plainly that I hadn’t. He explained the account had been frozen and that the bank would investigate the unauthorized application and charges. I asked him to keep the transfer blocked, disable the associated cards, preserve the records, and register a formal fraud dispute. Then I walked back into the lobby carrying copies of the documents. Tessa rushed toward me, asking whether the money had been released. I said no. She looked genuinely confused and explained that Mom had assured her I’d reconsidered my refusal and arranged the credit voluntarily. My parents had apparently told each of us a different story. Before I could fully absorb that, Dad took a typed letter from his jacket and offered me his silver pen. The letter stated that I’d authorized the account and every transaction, and it was dated the day before the application had been submitted. He wanted me to sign it immediately so the bank would release the money. When I refused, he warned that my mother could face criminal charges. For one terrible moment, I nearly took the pen. Then I looked at the backdated document and realized they hadn’t merely used my identity without permission—they had arrived prepared to make me falsely accept responsibility if their plan failed. I told Dad I wouldn’t sign. Kevin stepped out of his office and asked to examine the letter, but my father folded it away and ordered the family to leave. Tessa stayed behind. On the drive to her apartment, she admitted she’d believed our parents because they’d always promised to take care of her. I asked when she’d last reviewed her credit reports. She checked them while I sat beside her and found three unfamiliar accounts totaling approximately $57,000, all associated with my father’s business address. She stared at the screen and whispered, “They did it to me too.”
The discovery changed everything I thought I understood about my parents’ motives. Tessa and I reported the unauthorized accounts, secured our financial information, and provided records to investigators. Detective Carla Benson of the St. Louis County police eventually traced the transactions to a much larger problem. My father’s architecture firm, Harper and Vance, had been struggling for nearly four years after his business partner retired, two major projects fell through, and a costly lawsuit drained its reserves. Dad had concealed the firm’s deteriorating finances from nearly everyone, maintaining the appearance of success while falling behind on rent and reducing his staff. When conventional borrowing became unavailable, he began using credit opened in other people’s names. Two years earlier, my mother’s assistance with the applications had enabled him to obtain loans and credit cards using Tessa’s identity. She had been told the money was temporary financing for his company. When Tessa began planning her design studio and I refused to give her $80,000, Dad saw an opportunity to obtain another large credit line in my name. Some purchases genuinely supported Tessa’s proposed business, but equipment and approximately $18,000 in vendor payments benefited his architecture firm. Investigators also discovered that the attempted $45,000 transfer into Tessa’s studio account would have been followed by a scheduled transfer of $30,000 to my father’s company. My mother had set up that transaction using Tessa’s banking credentials, apparently believing it served a legitimate business purpose. Our family had been told the money was for my sister’s future; investigators found that much of it was intended to keep my father’s failing firm operating. Several days after the bank confrontation, Dad called and begged me to visit because Mom was distraught. I agreed only if Tessa came with me. When we arrived at their large house in Kirkwood, unpaid bills and final notices covered the dining-room table. Dad asked us to withdraw our fraud reports, saying the family could repay the money privately and avoid prosecution. Mom cried about the possibility of facing charges. Tessa asked whether she knew the firm’s actual financial position. When Dad’s hidden debts and business failures were explained, Mom appeared genuinely shocked. She admitted completing applications and verification steps, but said she’d trusted his assurances about the purpose of the borrowing. That didn’t erase her own responsibility for using our identities without permission. I asked Dad why he’d never simply told me he needed help. He said fathers were supposed to provide for their daughters, not admit failure to them. I told him that if he’d asked, I would have helped examine the finances, find professional advice, or consider restructuring and bankruptcy options. What I couldn’t accept was having my name used without consent. Tessa stood beside me and said that years of being protected from disappointment hadn’t prepared her to run a business, but that didn’t give anyone the right to expose her to unauthorized debts. Neither of us withdrew our fraud reports. We sought legal guidance, disputed the accounts through the appropriate lenders and credit-reporting agencies, and cooperated with investigators. The bank’s findings and the criminal proceedings proceeded separately from the family’s promises to repay. My mother ultimately faced identity-fraud and forgery charges, while my father faced more serious allegations involving bank fraud, conspiracy, and identity theft. Both entered guilty pleas. Mom received a probationary sentence with financial-crimes program requirements and court-ordered restitution. Dad received an eighteen-month federal custodial sentence followed by supervised release. His firm filed for Chapter 7 bankruptcy and closed, and his professional license was suspended. My parents sold their large house, settled what secured debts they could, and my mother moved into a smaller condominium in Maplewood. The court’s restitution orders established their obligations, while the banks and credit bureaus separately addressed the unauthorized accounts. I made sure the fraudulent debt wasn’t simply treated as mine because someone had used my name. None of this was painless. I hated watching my parents lose the life they’d spent decades building, but the consequences had begun with their decisions, not with my refusal to conceal them. Before Dad reported to prison, I drove him to the facility in Illinois. For much of the journey, we said very little. Finally, he admitted that he’d been terrified of appearing unsuccessful to the daughter he’d always called strong. He apologized for taking what he was too proud to request. When we reached the entrance, he asked whether I would write to him. I told him I would. That was my decision, just as reporting the fraud had been.
While my parents dealt with the legal aftermath, Tessa began rebuilding her plans. I introduced her to Denise Holloway at the Small Business Development Center, a practical, demanding adviser who insisted on actual budgets rather than attractive photographs. For months, the three of us worked through projected revenue, rent, inventory, insurance, taxes, staffing, and cash flow. Tessa negotiated an exit from the expensive studio lease she’d signed, sold or returned much of the furniture purchased during the fraudulent spending spree, and took a job at a paint store. She discovered she was exceptionally good at helping customers choose colors, and for the first time she began developing her professional skills without assuming someone would finance every decision. Eventually, she qualified for a $15,000 microloan and opened a smaller design studio on Cherokee Street, where the monthly rent was manageable. She painted the walls herself, refinished the floor, and kept the gold-lettered logo she’d designed years earlier. At the opening, our mother arrived carrying a fern for the window. Tessa accepted it quietly. Later, Mom handed me a letter and pencil sketch from Dad. He’d drawn the studio from Tessa’s descriptions and written that he was proud of her. Beneath the drawing he’d added a note calling me the load-bearing walls—the person who had offered honest support when everyone else supplied easy promises. I cried outside the storefront while Tessa studied the drawing and complained that Dad had gotten the ceiling wrong. Then she handed me her first business card and announced that she’d booked a consultation to redesign my kitchen. I was her client, she explained, and she intended to send a proper invoice at her full rate. I agreed. Over the following weeks, she transformed my outdated yellow kitchen into a warm, bright room with green cabinets, brass handles, and a reclaimed farmhouse sink. I paid every invoice on time. Our parents continued meeting their restitution obligations, and I kept writing to Dad while he served his sentence. We weren’t pretending the damage had disappeared. But for the first time in our family, help was becoming something offered, requested, and accepted openly rather than something silently taken for granted.
My kitchen is finished now, and beside the window hangs Dad’s drawing of Tessa’s studio. Every morning, I see it while the coffee brews. I still think about that first phone call from Lakeshore Federal and how readily I assumed a stranger had stolen my identity. The harder truth was that the people closest to me had grown so accustomed to my help that they’d stopped believing they needed my permission. I don’t regret refusing to sign the false authorization, and I don’t regret supporting my sister afterward. Those decisions came from the same place: I wanted my family to be safe, but I also wanted my own life to belong to me. Tessa now has a business she understands, Mom is rebuilding a smaller life, and Dad writes letters in which he finally admits when he needs something. I’m still the practical one. I still help when I can. But now, when someone asks, I get to decide. That difference means more to me than the money ever did.